Financing a Short-Term Rental on Lake Martin: What Counts and What Does Not
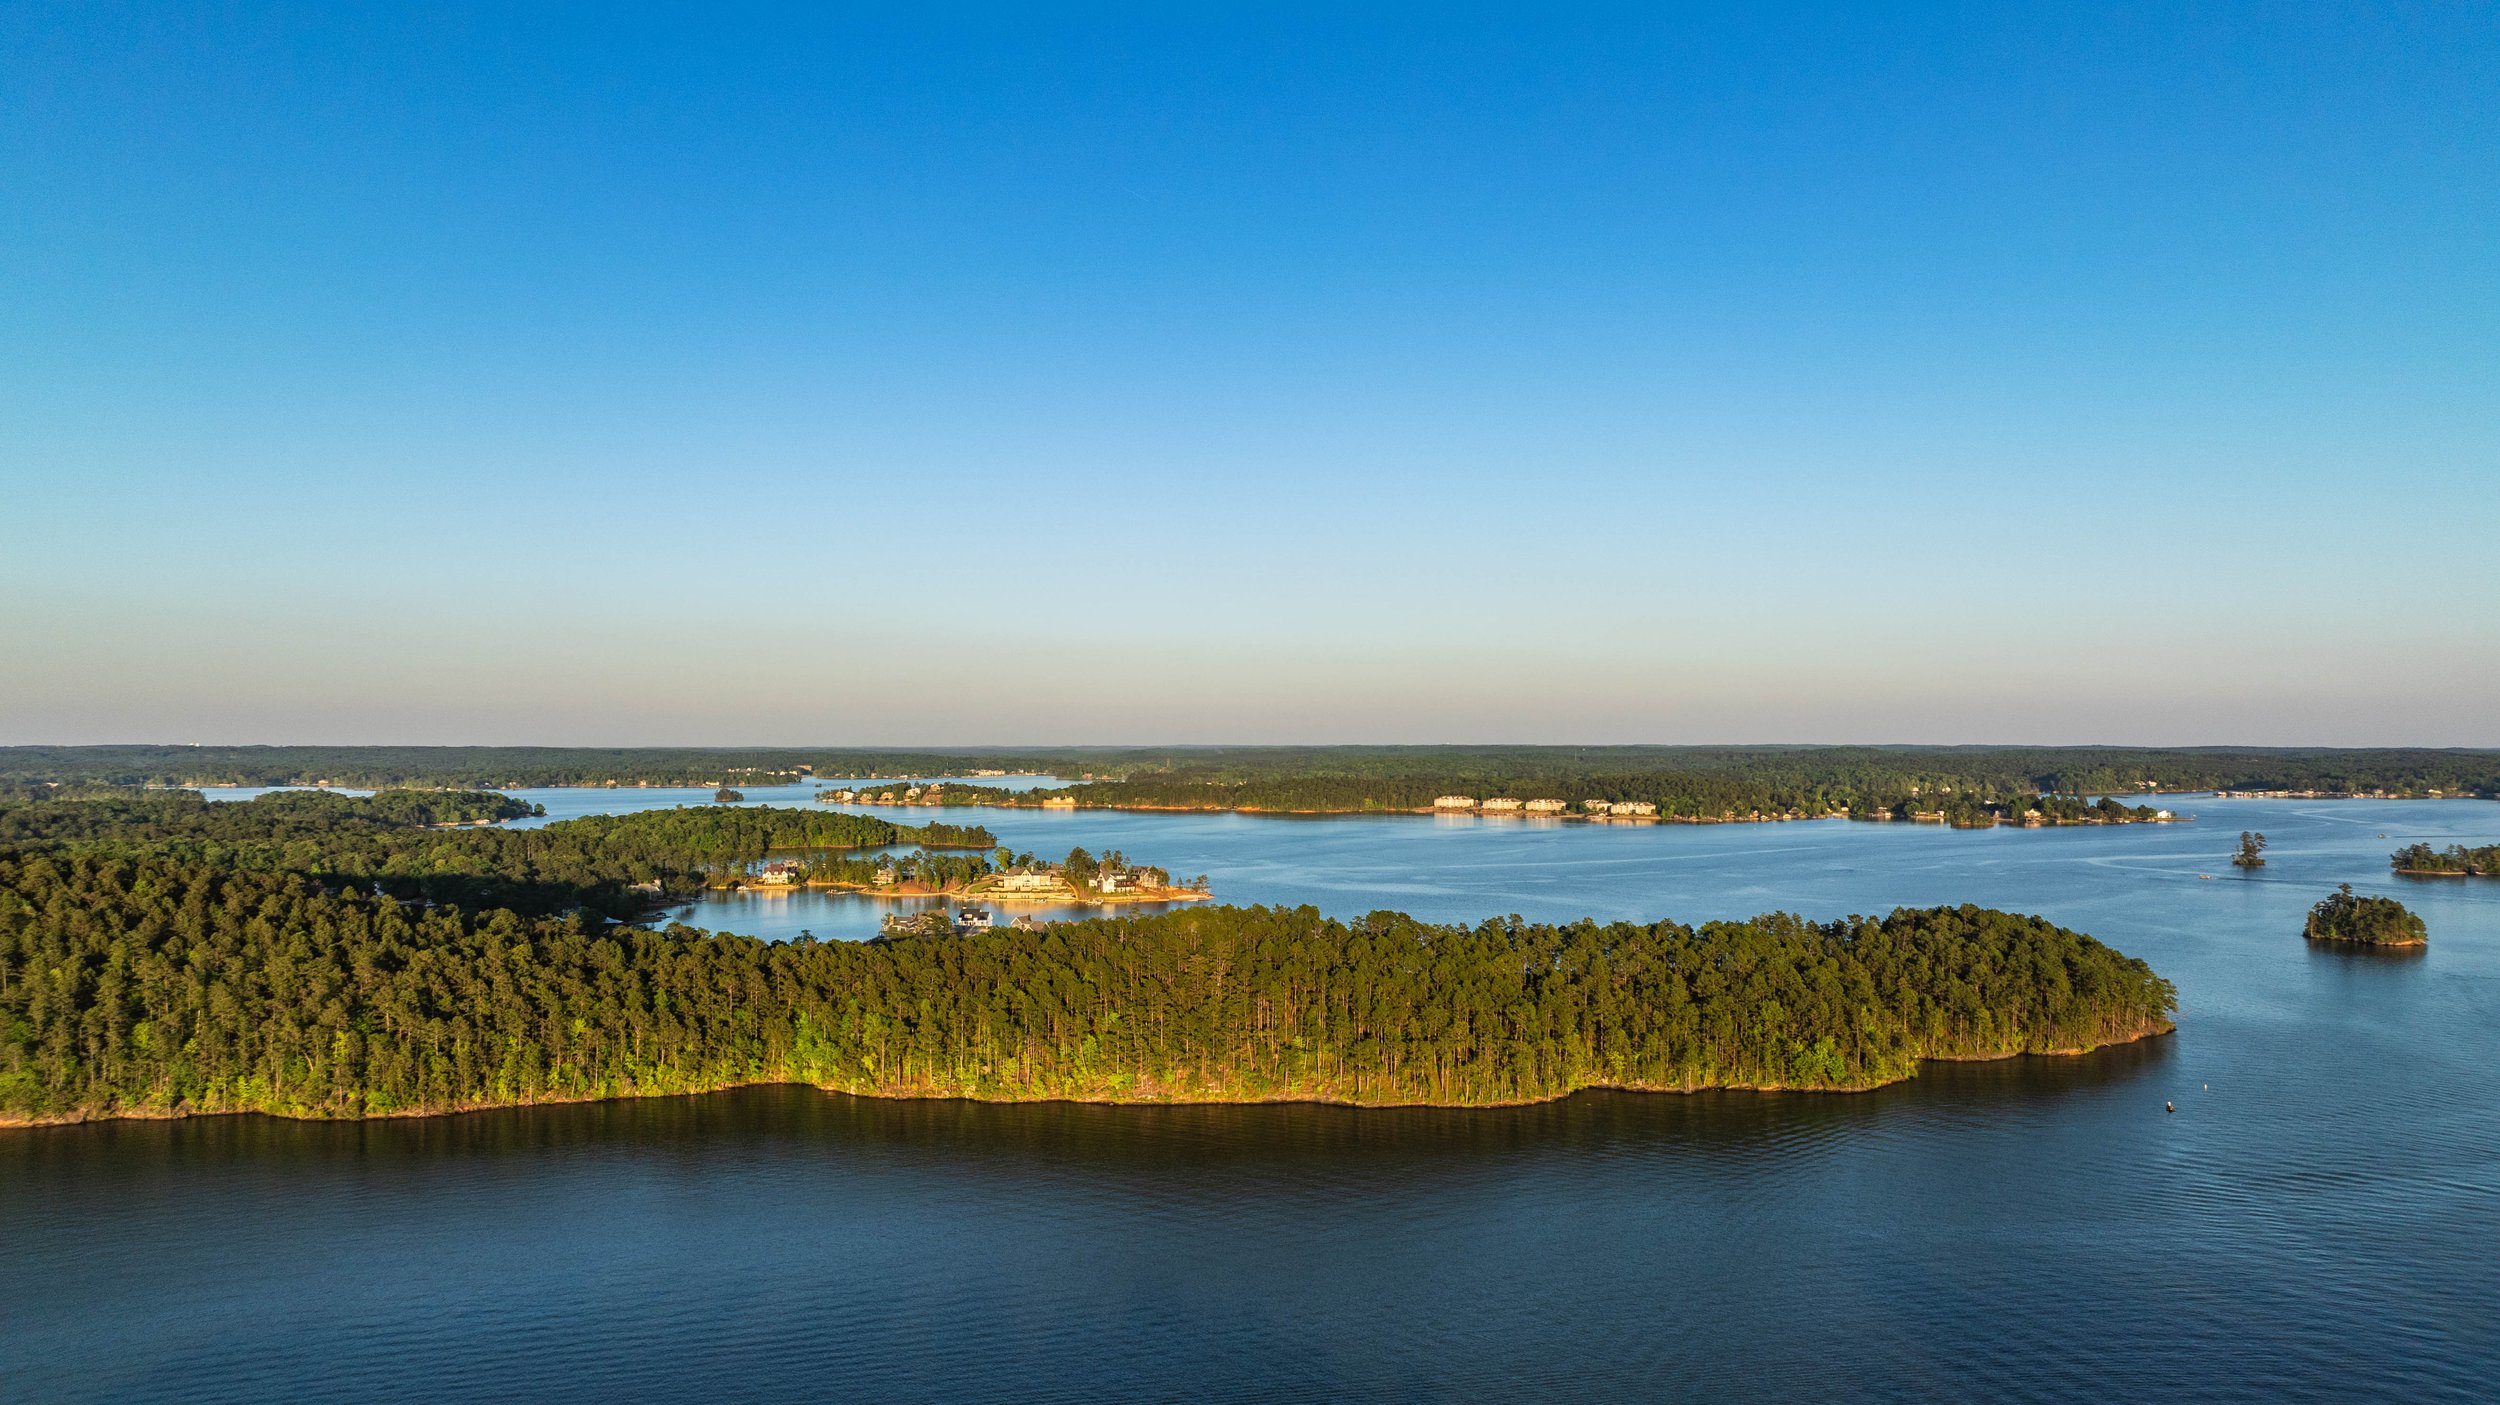
Photo: Southern Aerial Real Estate Media
Key Takeaways
This post is a 5 minute read.
Fannie Mae added a short-term rental income rule on September 2, 2026.
It covers one-unit investment properties only, not second homes.
Only half the nightly rent counts, and only against that home's own payment.
The rental has to be legal locally, including any permit or license.
Lake Martin waterfront prices often push buyers past conventional loan limits.
A DSCR loan is sometimes the better fit than a conventional one.
Almost every Lake Martin buyer says some version of the same thing. The house will pay for itself on summer weekends. Lenders have rarely agreed with that math. Until this month there was no clear conventional rule for counting nightly rental income. Fannie Mae published one on September 2, 2026. Every lender must use it for applications dated November 1 or later. Here is what it actually does for a lake house in Tallapoosa County.
What Lake Martin Rentals Actually Earn
Start with the full-year numbers, not the summer ones. Short-term rental data from Rabbu put the average nightly rate in Dadeville at $376 in April 2026. The Alabama average was $247. That premium is the good news. Occupancy is the other half of the story. Dadeville averaged 19 percent occupancy against 38 percent statewide. The seasonal swing explains it. The average listing grossed $8,998 in July and $424 in January. Fifty listings were active, and 78 percent of them advertised lake access. A lender looks at the whole calendar, not the Fourth of July.
Second Home or Investment Property
This is the fork in the road, and plenty of buyers pick wrong. A second home usually gets better pricing and a smaller down payment. But the new rule covers one-unit investment properties only. Rent from a second home cannot help you qualify. If you need the rental income to make the numbers work, you are buying an investment property. That means a larger down payment and different pricing. If you do not need the income, a second home may still be the cleaner choice. Settle this before you write the offer, not during underwriting.
Only Half the Rent Counts
The math is simple and deliberately conservative. Take the monthly gross rent figure. Multiply it by 50 percent. Subtract the full monthly payment on that house. That means principal, interest, taxes, insurance, and any association dues. Fannie Mae calls the result adjusted net rental income. The missing half is assumed to cover empty nights, cleaning, and repairs. A positive result offsets that home's payment and stops there. A negative result counts against you as a monthly debt. A standard one-year lease gets 75 percent instead of 50 percent. Nightly rentals pay for their flexibility with that 25 point haircut.
Where the Lender Gets the Rent Number
You do not need a rental history on a house you have not bought yet. The lender has two ways to set the number. One is a comparable rent schedule from the appraiser, built on standard long-term rents. The other is validated short-term rental data. That data has to cover three comparable short-term rentals nearby. It must show their daily, weekly, or monthly rates. It must also show how many days each one rented last calendar year. The data has to come from the MLS or a property management company. Screenshots from a booking site will not do. Around Lake Martin, a local rental manager is usually the fastest source.
Legal First, Income Second
None of this works if the rental is not allowed. The property must comply with every local registration and licensing rule. Check with the City of Dadeville or Alexander City before you go under contract. Alabama treats any stay under 180 days as taxable lodging. The state lodgings tax runs 4 percent in Tallapoosa County. Counties in the Mountain Lakes region pay 5 percent, and Tallapoosa is not one of them. Local lodging taxes stack on top of the state rate. Then read the subdivision covenants. A good number of Lake Martin communities limit or ban nightly rentals outright.
When the Price Pushes You Past the Limits
Lake Martin is not an entry-level market anymore. Lake Martin Realty reported a median waterfront sale price of $1,225,000 for the twelve months ending January 31, 2026. That was up 26 percent from $972,500 a year earlier. Inventory sat near five months of supply. The 2026 conforming loan limit on a one-unit Alabama property is $832,750. Plenty of lake purchases land above that line. Above it you are in jumbo territory, with tighter credit and reserve requirements. Our county-by-county look at the 2026 conforming loan limits shows where the cutoffs fall.
When a DSCR Loan Fits Better
Losing half the rent stings on a strong performer. A DSCR loan qualifies the property instead of the borrower. DSCR stands for debt service coverage ratio. The lender compares the property's rent to its payment and skips your tax returns. Some DSCR programs will underwrite to short-term rental income directly. Down payments usually start higher, and pricing is not conventional pricing. It is still often the better answer on a four or five bedroom lake house. Our guide to financing an investment property in Alabama covers how that structure works.
What to Have Ready Before You Offer
Bring documentation of your current housing payment. The lender needs it before any rental income can count at all. Map out the permit and license path for the city and the county. Ask the listing agent for the property's real booking history if it has one. If you already own rentals, pull last year's Schedule E. Twelve months of documented property management history changes how income gets treated. Then run both paths side by side. A conventional investment loan and a DSCR loan can give very different answers on the same house. Our Lake Martin mortgage guide covers the waterfront basics that apply either way.
Frequently Asked Questions
Can I use Airbnb income to buy a house on Lake Martin?
Yes, on a one-unit investment property that is legally permitted to operate as a short-term rental. Fannie Mae's rule took effect September 2, 2026. It is required for applications dated November 1, 2026 or later.
Does short-term rental income work on a second home?
No. The rule covers investment properties only. If you finance the lake house as a second home, nightly rent cannot be used to help you qualify.
How much of the nightly rent will a lender count?
Half. The lender takes 50 percent of the gross monthly rent and subtracts the home's full payment. The other half is assumed to go toward vacancy, cleaning, and upkeep.
What happens if the rental income is bigger than the payment?
It offsets that property's payment and nothing more. Surplus rental income is not added to your qualifying income under this rule.
Do I need short-term rental experience to qualify?
Not to buy. But using positive rental income as qualifying income generally requires twelve months of documented property management history.
Are short-term rentals allowed everywhere on Lake Martin?
No. Rules vary by city and county, and many subdivisions restrict nightly rentals in their covenants. Verify with the local government and read the covenants before you write an offer.
Trey Foshee NMLS #2654005 | Hunter McBride NMLS #2674392 | Joe Taunton NMLS #953010
Breeze Mortgage is powered by Edge Home Finance, LLC. NMLS #891464. Equal Housing Lender. This content is for informational purposes only and is not a commitment to lend. All loans are subject to credit approval, underwriting guidelines, and property eligibility requirements. Down payment assistance programs, availability, eligibility requirements, and funding are subject to change without notice. Contact Breeze Mortgage for current program details and to determine what options may be available for your specific situation.
