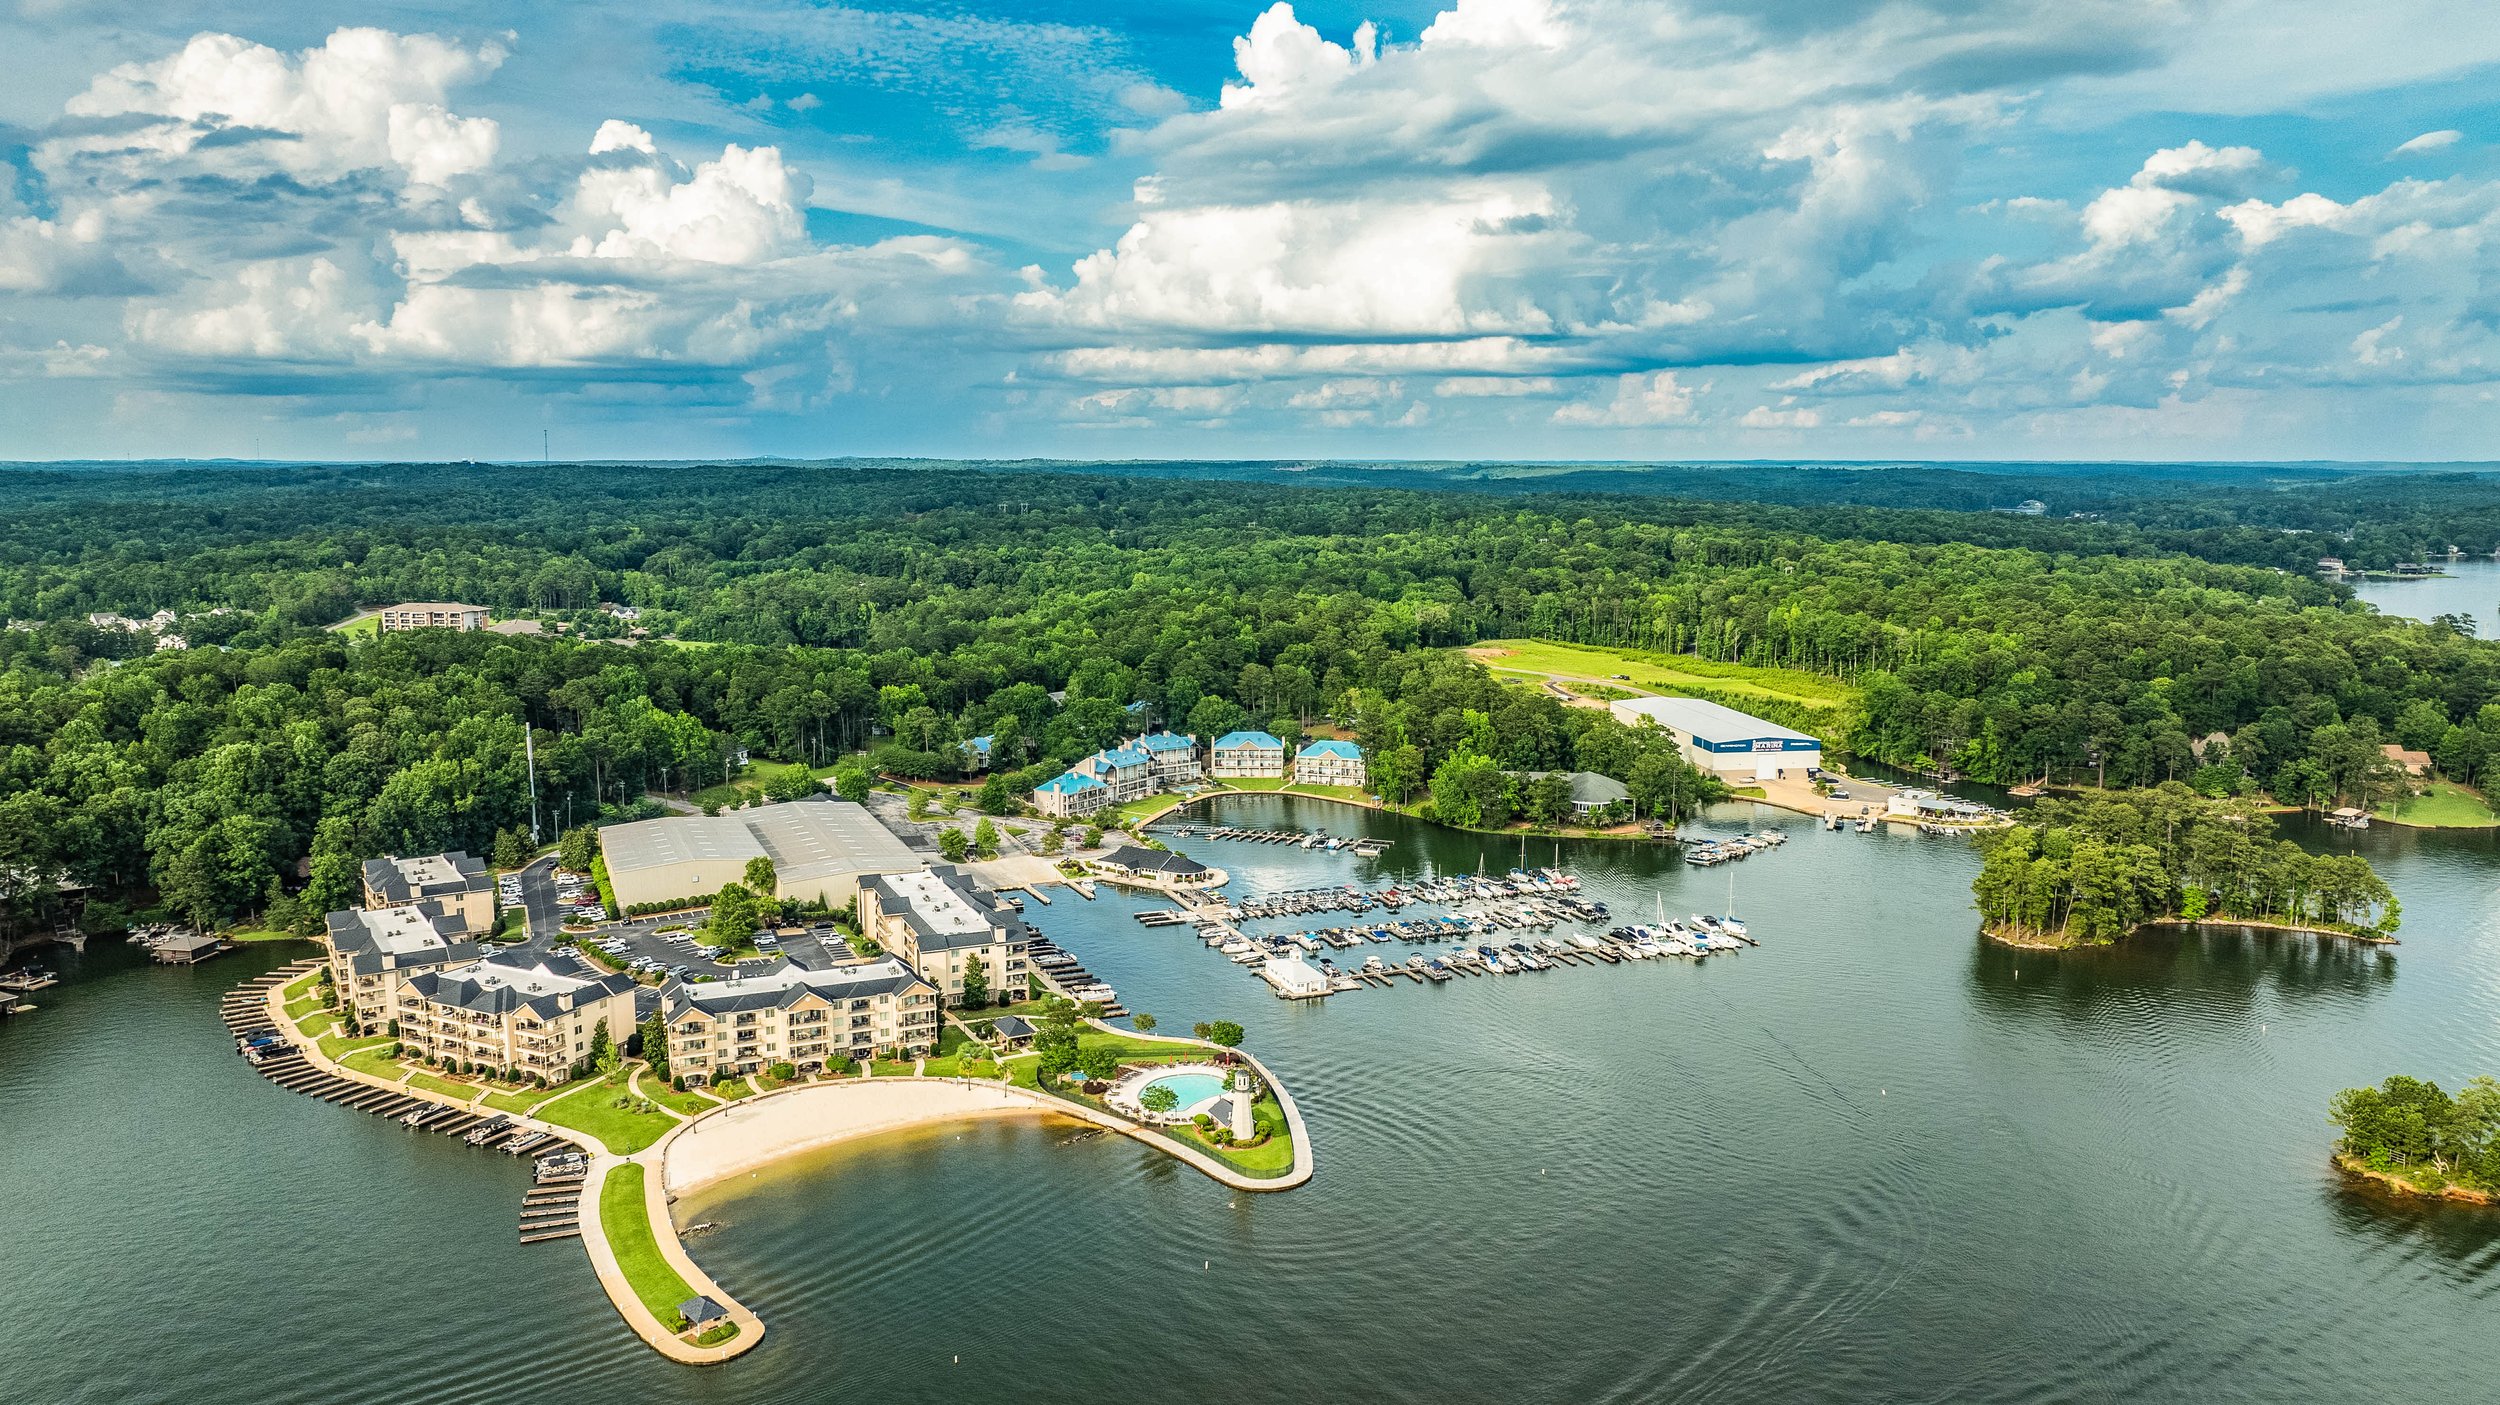
Photo: Southern Aerial Real Estate Media
Key Takeaways
This post is a 4 minute read.
A condo loan depends on the whole building, not only on you.
Lenders review the budget, reserves, insurance, and how many owners live there.
FHA can approve a single unit in some buildings that lack full approval.
Fannie Mae retired its Limited Review for applications dated August 3, 2026 or later.
Ask your lender to check the building before you make an offer.
Picture a buyer with strong credit who falls for a lakeside condo. Then the lender says the building will not qualify. It happens more than people expect. With a condo, the lender approves you and the building together.
This guide covers what lenders look at in a condo community. It also shows how to spot trouble early. Breeze Mortgage helps buyers across Alabama and Georgia, including the Lake Martin area.
Why the Building Matters as Much as Your Credit
When you buy a condo, you own the unit and share ownership of the common areas. Those include the roof, halls, parking, and grounds. A homeowners association, or HOA, collects dues and runs the building.
If the association is in poor shape, the loan carries more risk. Lenders look at the association the way they look at your income.
What Lenders Check in a Condo Project
Each loan program has its own list. Most of them cover the same ground.
Lenders usually review the annual budget and how much goes into a reserve fund. A reserve fund is savings the HOA sets aside for big repairs. They also check how many owners are behind on dues. Pending lawsuits and weak insurance can raise flags too.
Many also ask how many units are owner-occupied versus rented. A building full of rentals can be harder to finance.
What Changed for Conventional Condo Loans
Fannie Mae retired its Limited Review for applications dated on or after August 3, 2026. That was a shortcut for some owner-occupied units in established buildings. Most conventional loans on condos now need a Full Review.
A Full Review is a deeper look at the budget, reserves, insurance, repairs, and delinquent dues. Fannie Mae's guidance says the reserve test is 10 percent of the annual budget. Industry summaries say that figure is scheduled to rise to 15 percent in January 2027.
Fannie Mae also looks for critical repairs. Examples include roof failure, water leaks, and unsafe balconies. An unfunded repair over $10,000 per unit can make a project ineligible.
None of this means a good building is a problem. It means the paperwork matters more now.
FHA Condo Rules and Single-Unit Approval
FHA keeps its own list of approved condo projects. Approval typically lasts three years before it needs renewal. Published guidelines call for at least 50 percent of units to be owner-occupied. No more than 15 percent of owners can be 60 days behind on dues.
If a building is not on the approved list, FHA may allow a single-unit approval. Industry guides describe a few conditions. The building usually needs at least five units. It also has to be existing construction. FHA loans can make up only about 10 percent of the units.
Our guide to FHA loans in Alabama explains the basics. VA keeps a separate list of approved condos, so ask us about that if you are a veteran.
Lake Martin and Gulf Coast Condos
Lakeside condo communities near Alexander City and Dadeville bring extra questions. Is the unit in a flood zone? Does the dues amount include the boat slip? Who insures the building?
The Gulf Coast shows how fast the picture can change. A May 2025 report cited Alabama Center for Real Estate data showing condo sales fell 17 percent in 2024. It also said nearly 70 Alabama condo complexes were ineligible for Fannie Mae backing at that time. Insurance costs were a major reason.
Rental rules deserve a look too. Some associations limit short-term stays. If you plan to rent a unit, read our post on short-term rental financing on Lake Martin first.
The Monthly Cost Is More Than the Loan
HOA dues are part of your monthly budget. Lenders count them when they figure your debt-to-income ratio. That ratio compares your monthly debts with your monthly income.
Dues are not the same as escrow. Escrow is the account that holds money for your property taxes and insurance. Our post on escrow accounts in Alabama shows how those pieces fit together.
You will likely need your own condo insurance policy for the inside of your unit. The HOA policy usually covers the building. Ask what it does not cover.
How to Protect Yourself Before You Make an Offer
Start by asking for the HOA budget, the latest meeting minutes, and the reserve study if one exists. Ask whether any special assessments are planned. A special assessment is a one-time charge on every owner for a big repair.
Then call your loan officer before you sign a contract. We can often tell you early whether a building is likely to work. Guidelines change often, so confirm current rules with us.
Condo Loan FAQ
Can I use an FHA loan to buy a condo in Alabama?
Yes, if the building is on FHA's approved list or the unit qualifies for single-unit approval. Rules and eligibility vary, so ask a loan officer to check.
What is a Full Review on a condo loan?
It is a lender's deeper check of the HOA budget, reserves, insurance, repairs, and delinquent dues. Fannie Mae now uses it for most conventional condo loans in established buildings.
Why was my condo loan denied when my credit is strong?
The building may not meet the program's rules. Common reasons include low reserves, unfunded repairs, high delinquency, or too many rentals.
Are HOA dues included in my mortgage payment?
Not usually. Lenders count the dues in your debt-to-income ratio, but you typically pay the HOA directly. Property taxes and insurance may be escrowed.
Do I need separate insurance for a condo unit?
Usually yes. The HOA carries a master policy for the building. You typically need your own policy for your belongings and the interior of the unit.
Ready to see if a condo fits your plan? Reach out to Breeze Mortgage for a simple, stress-free look at your financing options.
Trey Foshee NMLS #2654005 | Hunter McBride NMLS #2674392 | Joe Taunton NMLS #953010
Breeze Mortgage is powered by Edge Home Finance, LLC. NMLS #891464. Equal Housing Opportunity. This content is for informational purposes only and is not a commitment to lend. All loans are subject to credit approval, underwriting guidelines, and property eligibility requirements. Down payment assistance programs, availability, eligibility requirements, and funding are subject to change without notice. Contact Breeze Mortgage for current program details and to determine what options may be available for your specific situation.
