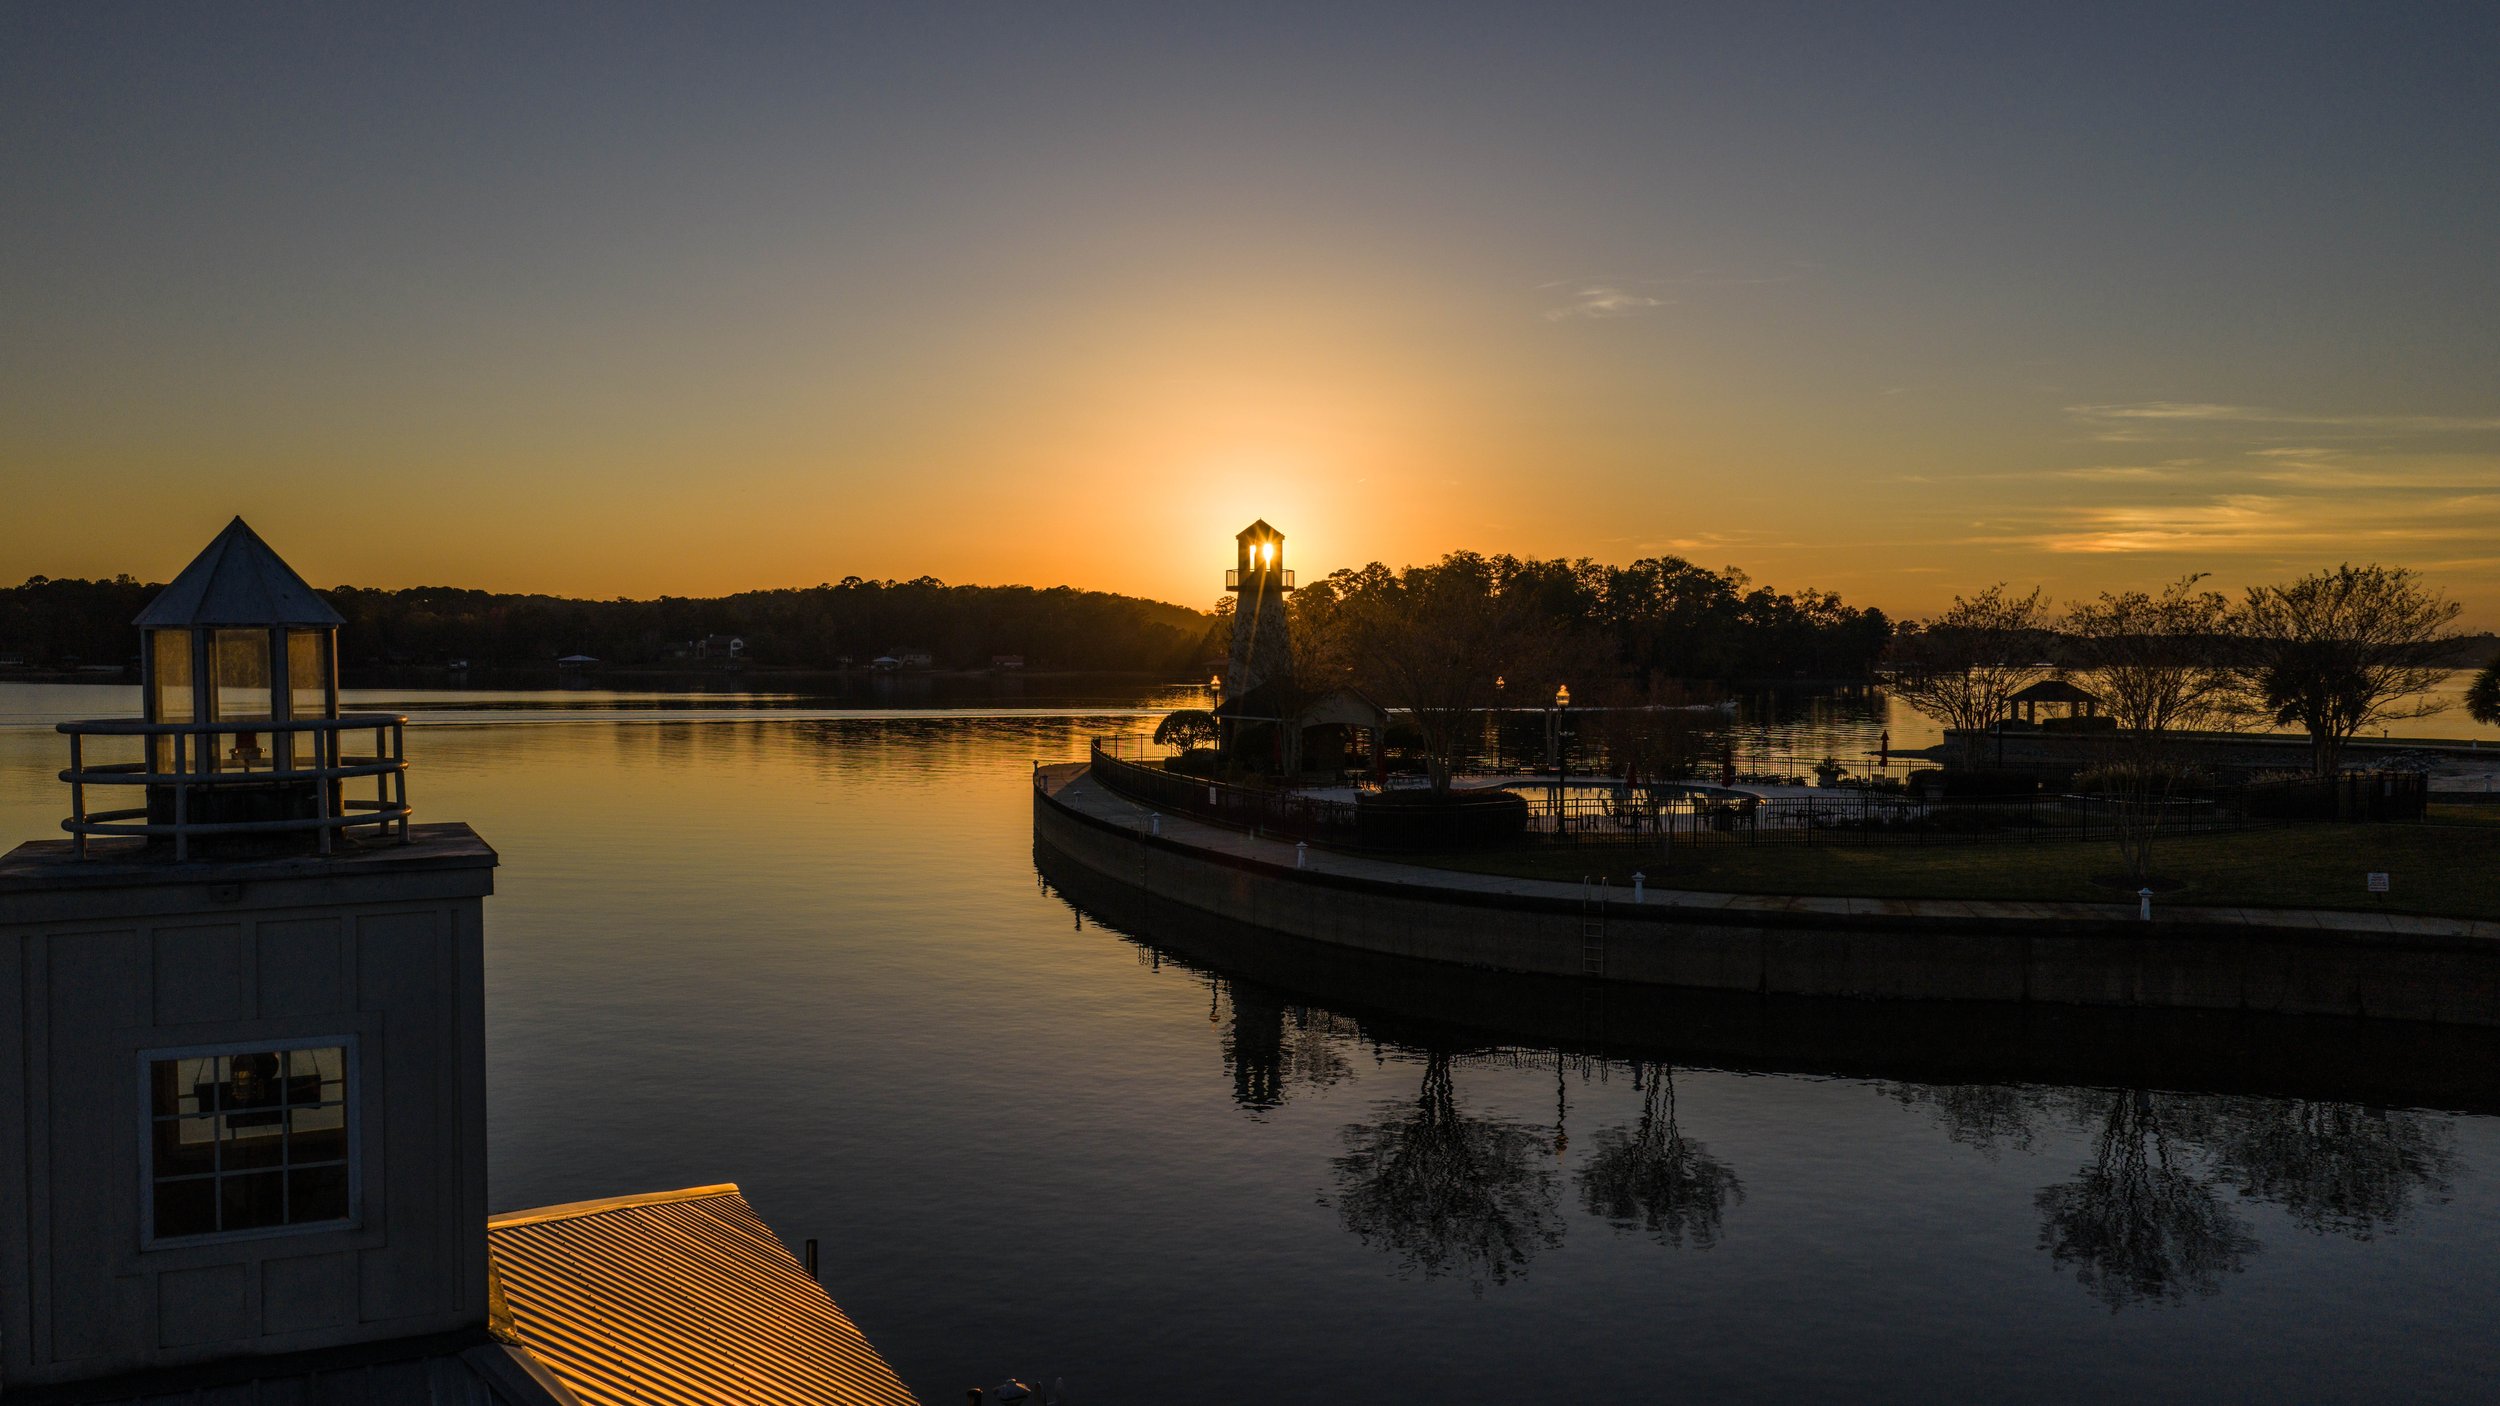
Photo: Southern Aerial Real Estate Media
Key Takeaways
This post is a 4 minute read.
Lake Martin lot prices swing widely, and water access often drives the price more than acreage does.
Bare land loans usually ask for a larger down payment and a shorter repayment than home loans.
A construction-to-permanent loan can pay for the lot and the build under one loan.
Confirm septic approval, utilities, and lake rights before you close on the land.
Talk with a loan officer before you sign a contract on a lot.
Two lots on War Dance Court near Dadeville were listed this summer at $35,000 each. An 11.55 acre waterfront parcel on Williams Road in Alexander City was listed at $1,290,000. Both are "land at Lake Martin." The gap between them is the whole story of buying a lot here.
On a typical day, a lake listing site shows about 60 lots and land parcels next to roughly 230 homes. That is a small pool, so good lots move. It helps to know how the financing works before you find one.
Why Lake Martin Lots Are Priced So Differently
Three things drive the price. The first is distance to the water. The second is what already sits on the lot, such as a driveway, a septic system, or utilities. The third is what the shoreline allows.
Lake Martin has about 880 miles of shoreline across Tallapoosa, Elmore, and Coosa counties. Some shoreline property sits on land that Alabama Power leases or controls. Frontage does not always come with full ownership rights.
An inland lot is mostly a buildable piece of ground. A shoreline lot is a different kind of purchase. Treat them as two separate decisions.
What "Water Access" Can Really Mean
Listings use this phrase loosely. It can mean a private shoreline. It can mean a community dock or a shared beach. It can also mean a deeded path to the lake.
Each one has a different value and different rules. Ask for the deed language and any community documents. A real estate attorney can confirm what you would actually own.
If you want a dock later, read our post on Lake Martin dock permits. A permit is a license to use the shoreline. It is not property you can count on passing to a buyer.
Septic, Water, and Power Come First
Many lots outside town limits have no sewer line. That means the home will need a septic system. In Tallapoosa County, the Alexander City branch of the health department handles onsite sewage applications and permits.
The process usually starts with a site and soil evaluation. A lot that cannot support a system is worth far less than the listing suggests. Ask the seller for any existing permit or soil report.
Then confirm who supplies water and power. Find out how far the lines must run to reach the building site. Extending lines can add real cost to the project.
Three Ways to Pay for the Lot and the House
The first option is a loan for the land alone. Lenders see vacant land as higher risk because no house secures the loan. Expect stricter terms, usually a larger down payment and a shorter repayment than a home loan.
The second option is a construction-to-permanent loan that includes the lot. One loan pays for the land, then pays the builder in stages. It converts to a regular mortgage when the home is finished. Our guide to new construction loans explains the draw process.
The third option applies if you already own the lot. In many cases, the value in land you own can count toward the cost of building. The exact treatment depends on the program, so ask early.
Two timing rules are worth knowing. Some guidelines require you to hold title to a lot for at least six months before a cash-back refinance. Builds that run past 18 months may also need a different loan structure under Fannie Mae rules.
Questions to Ask Before You Make an Offer
Is the lot buildable under county and community rules? Many lake neighborhoods have covenants. These can set a minimum home size or require approval of your plans.
Is any part of the lot in a flood zone? Lakeside property can need extra insurance, and that changes your monthly budget.
Are there easements that cross the land? Utility and access easements can limit where the house can sit.
Then get pre-approved before you sign. Contract deadlines on land can be short. Financing for a lot also works differently from a standard home purchase.
Lake Martin Lot Loan FAQ
Can I get a loan for vacant land at Lake Martin?
Yes, options exist. Land-only loans are usually stricter than home loans. A loan officer can compare them with a construction loan that includes the lot.
What is a construction-to-permanent loan?
It is one loan that covers the build in stages. When the home is finished, it converts to a regular mortgage. Some versions can also include the cost of the lot.
Do I need a septic permit before I buy a lot in Tallapoosa County?
Buying does not require one. It is smart to check first, because a lot that cannot pass is hard to build on. The Alexander City health department branch handles septic applications.
Does waterfront mean I own the shoreline?
Not always. Your rights depend on the deed and on Alabama Power's shoreline rules. Ask an attorney to review before you close.
Can I use land I already own toward a new home loan?
Often, yes. The value in the land can help with the project cost. Treatment varies by program, so confirm the details with a loan officer.
Thinking about a lot at Lake Martin? Reach out to Breeze Mortgage for a simple, stress-free look at your financing options.
Trey Foshee, Mortgage Loan Originator, NMLS #2654005 | Hunter McBride, Mortgage Loan Originator, NMLS #2674392 | Joe Taunton, Mortgage Loan Originator, NMLS #953010
Breeze Mortgage is powered by Edge Home Finance, LLC | NMLS #891464 | www.nmlsconsumeraccess.org. Edge Home Finance, LLC is a mortgage broker, not a direct lender or creditor. Licensed in 49 states and D.C. (Not licensed in NY). Edge Home Finance, LLC does not arrange, solicit, or originate mortgage loans for real property located in the State of New York. Equal Housing Opportunity. This content is for informational purposes only and is not a commitment to lend. All loans are subject to credit approval, underwriting guidelines, and property eligibility requirements. Down payment assistance programs, availability, eligibility requirements, and funding are subject to change without notice. Contact Breeze Mortgage for current program details and to determine what options may be available for your specific situation.
